What is the scope and industry significance of the Laboratory Glassware Market?
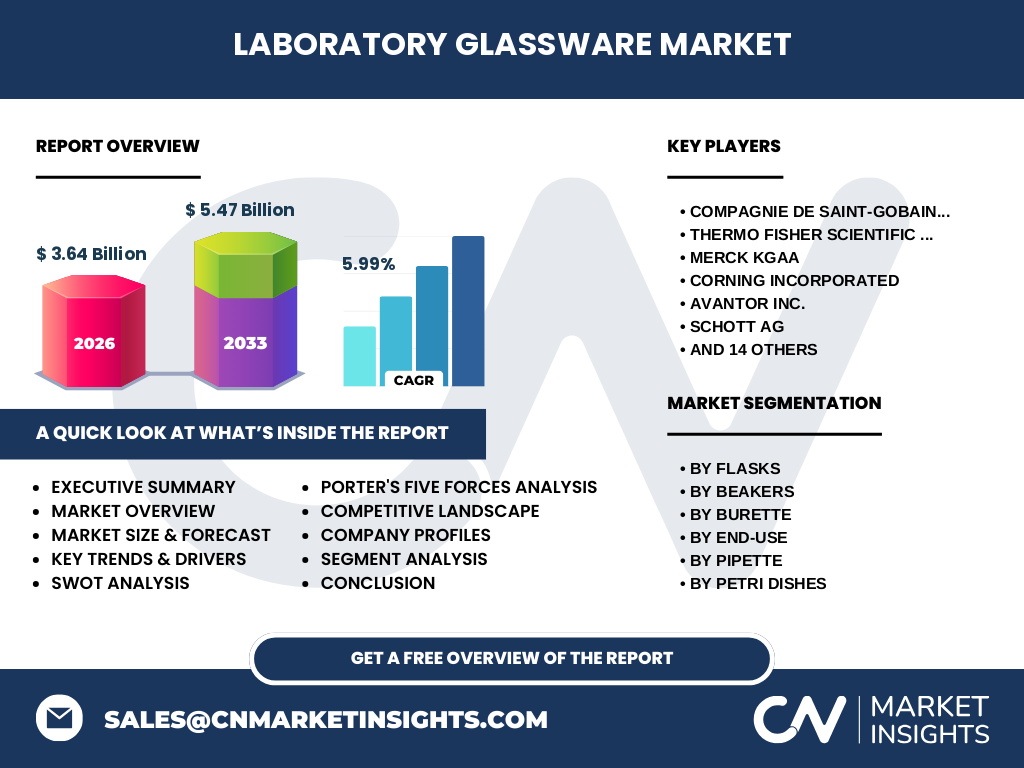
Our analysis indicates that the Laboratory Glassware Market is valued at $3.64 Billion in 2026, underpinning critical R&D and quality control workflows. This sector encompasses precision-engineered borosilicate vessels—ranging from Erlenmeyer flasks to graduated burettes—essential for chemical inertness and thermal shock resistance across pharmaceutical, academic, and industrial testing facilities globally.
Structural Growth Drivers and Restraints
The market is propelled by surging R&D investments in biotechnology and stringent drug safety regulations enforced by bodies like the FDA and EMA. However, growth is restrained by fragile supply chains for high-purity raw quartz and competition from disposable plasticware in routine clinical diagnostics, challenging manufacturers to emphasize sustainability.
The Shift Toward High-Purity Borosilicate and Customized Assemblies
Emerging trends reveal a pronounced shift toward ultra-low expansion borosilicate glass and custom-fabricated reactor assemblies. Leading innovators like Schott AG and Corning Incorporated are capitalizing on this by developing specialized glass coatings that prevent leaching during aggressive biochemical syntheses and volatile organic compound testing.
Pandemic Resilience: COVID-19 Impact and Recovery Trajectory
The COVID-19 pandemic caused severe supply chain bottlenecks for basic apparatus like volumetric flasks and Pyrex beakers. The post-pandemic recovery trajectory has accelerated remarkably, driven by vaccine development pipelines and massive governmental funding poured into national public health laboratories and diagnostic infrastructure.
Competitive Benchmarking in the Laboratory Glassware Market
The competitive landscape features a mix of multinational conglomerates and specialized precision glassmakers. Giants such as Thermo Fisher Scientific Inc., Merck KGaA, and DWK Life Sciences Limited dominate through extensive distribution networks, while regional players like Borosil Limited and Glassco Laboratory Equipment Pvt. Ltd. capture share via cost-effective manufacturing.
Executive Summary of Laboratory Glassware Market Dynamics
Synthesizing our research, the Laboratory Glassware Market represents a robust foundation for modern science. Driven by expanding biotech hubs and rigorous analytical standards, the sector demonstrates strong fundamentals that make it a compelling target for strategic stakeholders seeking stable, long-term returns.
Market Forecast and Long-Term Projections
Based on our econometric modeling, the Laboratory Glassware Market is projected to expand from $3.64 Billion in 2026 to $5.47 Billion by 2033, registering a steady CAGR of 5.99%. This sustained trajectory reflects continuous capacity expansion in pharmaceutical manufacturing and advanced academic research.
Comprehensive Segmentation Analysis
Segmentation is categorized by product types including Pipettes, Flasks (Erlenmeyer, Volumetric, Florence, Boiling), Beakers (Low-form, Tall-form), Burettes, Storage Containers (Reagent bottles, Desiccators), Petri Dishes, and other products like Test Tubes and Condensers. End-uses span Research Institutes, Pharma/Biotech, Hospitals, CROs, and Food & Beverage, distributed via Brick-and-Mortar and E-Commerce channels.
Regional Market Analysis and Geographic Distribution
Geographically, demand is concentrated in North America and Europe due to densely clustered pharmaceutical hubs and stringent compliance mandates. Meanwhile, the Asia-Pacific region is emerging as the fastest-growing territory, propelled by expanding contract research organizations and rising government investments in life sciences infrastructure in India and China.
In-Depth Regional Review of High-Growth Zones
Our regional deep-dive highlights North America as the revenue leader, anchored by robust R&D budgets in biotech clusters. Concurrently, the Asia-Pacific market exhibits exceptional dynamism, where local manufacturers like Abdos Labtech Private Limited leverage low-cost labor and proximity to burgeoning chemical industries to capture domestic and export volume.
Strategic Positioning of Key Market Participants
Industry leaders maintain strategic dominance through product differentiation and portfolio expansion. Companies like Gerresheimer AG and Compagnie de Saint-Gobain S.A. focus on high-end pharmaceutical packaging and technical glass, while Chemglass Life Sciences LLC and Ace Glass Incorporated target specialized academic and industrial custom glassware synthesis needs.
Porter's Five Forces Analysis of Competitive Intensity
Porter's framework reveals moderate-to-high rivalry among established industry leaders, counterbalanced by moderate supplier power over raw silica and boric acid inputs. The threat of substitutes is notably low in high-temperature or corrosive applications where plastics fail, though high buyer switching costs help stabilize long-term vendor contracts.
SWOT Analysis of the Laboratory Glassware Sector
Key strengths include unmatched chemical resistance and optical clarity of borosilicate materials. Weaknesses involve inherent fragility and high freight logistics costs. Opportunities abound in emerging biotech markets across Southeast Asia, while threats loom from stringent environmental regulations on glass manufacturing emissions and alternative synthetic polymers.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw material extraction of silica sand, soda ash, and limestone. Midstream activities involve high-temperature furnace melting, precision annealing, and automated optical inspection by firms such as Kavalierglass AS. The downstream flow reaches end-users through specialized B2B distributors, digital marketplaces, and direct-to-laboratory supply agreements.
High-Potential Investment Insights
Investors should focus on manufacturers incorporating automated optical defect-detection systems and eco-friendly electric glass-melting furnaces. Companies targeting high-purity bioprocessing applications and digital inventory-managed distribution channels present the highest alpha potential within this evolving industrial landscape.
Conclusion and Strategic Takeaways
The Laboratory Glassware Market proves that traditional materials remain irreplaceable in precision science. With a projected expansion to $5.47 Billion by 2033, success in this sector hinges on advanced thermal engineering, supply chain resilience, and alignment with fast-growing pharmaceutical and biotech end-user segments.
Research Methodology and Baseline Triangulation
Our baseline estimates are derived by triangulating primary stakeholder interviews with C-level executives across firms like Schott AG and Corning Incorporated, combined with exhaustive trade registry data, customs import-export logs, and secondary macroeconomic indicators tracking global life science capital expenditures.
Scope of the Report and Analytical Parameters
This report covers global revenue performance for the Laboratory Glassware Market from 2027 to 2033, utilizing 2026 as the base evaluation year. Parameters encompass all standard and custom borosilicate apparatus sold through direct and indirect channels, excluding consumer-grade kitchenware and generic industrial flat glass.
Recent Industry Developments and Strategic Partnerships
Recent market dynamism includes major players investing in green-energy melting technologies to reduce carbon footprints. Strategic moves feature acquisitions of boutique precision glassblowers by entities like DWK Life Sciences Limited, and expanded e-commerce distribution partnerships initiated by Globe Scientific Inc. to streamline direct laboratory procurement.